

Rocco - Fast Cash Advance

- 1.38K Reviews
- 4.1
- Downloads
- 100,000+
Our take on Rocco - Fast Cash Advance from Appgk
I approached Rocco - Fast Cash Advance as a practical finance app rather than something to open casually. Its purpose is straightforward: it brings cash advance and personal finance services into a mobile experience. That can be useful when a household is trying to manage a short gap before payday, but it also means the app deserves more careful handling than an ordinary budgeting tool. Money decisions affect everyone sharing a home, even when only one person creates the account.
My main impression is that Rocco is best understood as a private tool for one adult’s financial situation, not as a shared household wallet. I can see why someone would install it when an unexpected expense arrives, yet I would not hand a phone to another family member and assume the app is suitable for joint use. The important questions are who owns the account, who reviews the terms, who receives communications, and whether everyone involved understands that a cash advance is a financial obligation rather than extra income.
Using Rocco when a household needs a clear money boundary
A realistic example is a household facing an awkward timing problem: a necessary bill arrives before regular income, while another person in the home is helping with groceries or transport. In that situation, one adult might use Rocco to explore a cash advance and then explain the decision to the household. The app can serve as the private starting point, while the conversation about repayment stays outside it.
That separation is important. I would not treat the app as a family budgeting board, a shared savings account, or a way for several people to make decisions inside one profile. The store summary presents cash advance and personal finance services, so I would keep expectations focused on those functions. If what you really need is shared bill tracking, joint spending categories, or a family savings plan, a conventional budgeting app or bank feature may fit better.
Best Parts of Rocco - Fast Cash Advance
Things to Keep in Mind About Rocco - Fast Cash Advance
The household scenario also exposes a trade-off that is easy to miss. A fast financial service can reduce the stress of an immediate shortfall, but it can make a recurring money problem feel solved when it has only been moved forward. I would use Rocco to investigate an urgent option, not to normalize borrowing for ordinary weekly spending. Before proceeding, I would write down the amount needed, the reason for it, and the date on which repayment would be realistic.
The most useful habit is to decide the repayment plan before requesting help. That simple step changes the app from an impulse button into part of a controlled decision. If the plan depends on another household member’s income, I would discuss it first rather than assuming that person will cover the difference later.
News and Features Related to Rocco - Fast Cash Advance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What I would do before creating an account
Rocco is free to install, which makes trying the app less intimidating. Still, free access should not be confused with a free financial service. Cash advance products can involve conditions, eligibility checks, repayment expectations, or costs that matter far more than the download itself. I would read every screen carefully and avoid rushing through any consent or confirmation step simply because the need feels urgent.
I would also prepare the phone before setup. On a shared device, I would use the adult’s own phone profile or a clearly separated user space where available, keep the screen locked, and avoid saving sensitive information where another person can casually see it. I would not let a child or teenager complete the application on behalf of an adult. Even if the device belongs to the whole household, the financial identity behind the account belongs to one person.
Don't want to read the full review?
Another practical boundary is notification awareness. Financial messages can appear on a lock screen or in a notification drawer, so I would check the phone’s privacy settings before signing in. I would also avoid discussing account details in a group chat or leaving screenshots in a shared photo folder. These are not special Rocco features; they are sensible precautions for any app handling personal finance information.
The current version is 3.0.0, and the app runs on Android 8.0 or later. That makes device compatibility worth checking before planning around it, especially in a household where an older phone is passed between family members. I would install it only on a device that receives security updates and has enough privacy protection for financial use. A compatible operating system is necessary, but it does not by itself make a shared phone a secure account environment.
Screenshots
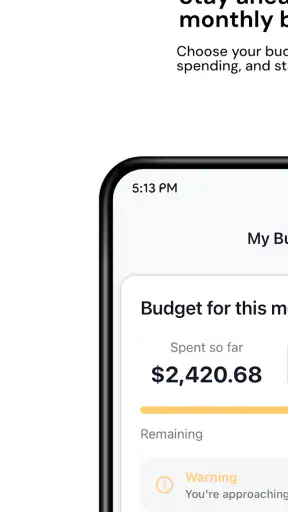
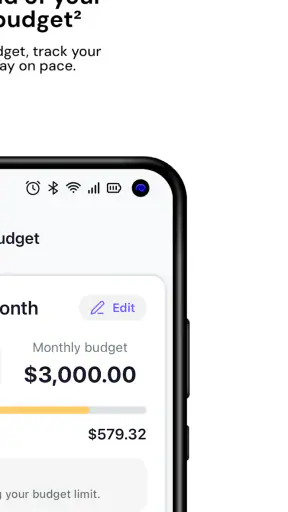
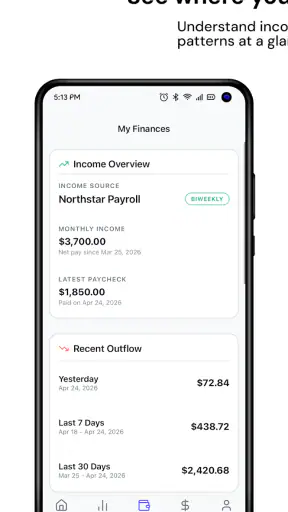
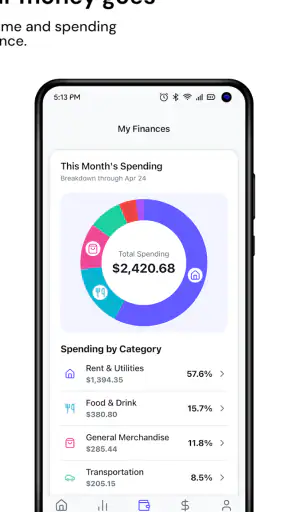
Coordinating without turning one account into a family account
Rocco can be part of a household conversation without becoming a shared login. I would have the account holder summarize the important details after reviewing them: how much is being considered, what the repayment timing looks like, and what household expense the money is meant to cover. That gives everyone affected a chance to understand the decision without passing passwords or personal documents around.
This approach is especially helpful for couples or relatives who divide expenses but keep separate financial identities. One person can handle the application while both people agree on the household consequence. If the money is intended for rent, utilities, or food, I would compare that plan with the existing budget first. If the advance is meant to cover another debt, I would pause and consider whether a creditor conversation, payment arrangement, or temporary spending cut would be safer.
I would not use a shared device as a substitute for coordination. A family member opening the app “just to check” can easily see private information or make a decision without understanding the consequences. The cleaner workflow is simple: one account holder, one person responsible for reviewing the terms, and a separate household discussion about the repayment impact.
There is also a useful distinction between access and accountability. Sharing a phone may be convenient, but it blurs who is responsible for an application or a confirmation. Keeping the account tied to the person making the financial decision avoids that confusion. If two adults need separate assistance, I would expect each person to evaluate their own situation rather than combining activity under one profile.
Age, trust, and the right person to use the app
The app carries an Everyone content rating, but that label should not be read as a recommendation for children to use a cash advance service. The subject itself is adult financial activity. In my view, the appropriate user is an adult who understands borrowing, can evaluate repayment, and is prepared to protect personal information. A young person might see the app on a family tablet, but that does not make it suitable for independent use.
For parents, the safest household rule is to explain what the app is before allowing access to the device. I would say plainly that a cash advance is not a gift, prize, or allowance. I would also keep the account holder’s email, phone access, identity information, and financial decisions separate from a child’s profile. The goal is not to make the app mysterious; it is to prevent accidental action and teach a realistic view of short-term borrowing.
Trust matters between adults too. If a partner is helping with household finances, that does not automatically mean they should use the other person’s login. I would rather review information together while the account holder remains in control. That protects both people: the account holder knows what was submitted, and the helper is not put in the position of making an unclear commitment.
Rocco may be less suitable for someone who wants a full financial dashboard. Its identity is centered on cash advance and personal finance services, not on replacing a bank account, credit counselor, or comprehensive household ledger. Someone trying to understand long-term spending patterns may get more value from a dedicated budgeting system, while someone facing serious debt may need direct advice from a qualified financial professional.
Where the app fits beside ordinary alternatives
The usual alternative to a cash advance app is often an overdraft facility, a credit card, a bank loan, an employer-based option, or simply asking a bill provider for more time. Each choice has different terms and risks. Rocco’s appeal is convenience: it puts a financial service on a phone and may feel easier to explore than visiting a branch or making several calls.
That convenience is also the main reason I would slow down. A bank account gives a broader view of available money and scheduled payments. A budgeting app helps reveal whether the problem is a one-off timing issue or a pattern. A credit card may already be familiar to the user, while a payment arrangement could avoid borrowing altogether. I would compare these routes before accepting any offer rather than assuming the fastest screen flow is the cheapest or safest answer.
For a household, a spreadsheet can sometimes be more useful than another financial product. Listing upcoming income, essential bills, food, transport, and existing repayments may show that the needed amount is smaller than first thought. It may also reveal that a cash advance would leave too little for the next week. Rocco can help someone explore an option, but it cannot replace that broader calculation.
One non-obvious trade-off is emotional rather than technical: a polished mobile experience can make a serious choice feel routine. I would treat each confirmation as if I were signing a paper form. Read the amount, timing, repayment language, and any applicable cost before moving forward. If a household member cannot explain the decision in plain language, that is a sign to stop and review it again.
My experience with the app’s practical fit
Rocco has a clear audience: adults looking for cash advance or personal finance services in a mobile format. Its 4.1 average from around four thousand ratings suggests that many users find value in the experience, while the roughly one thousand four hundred written reviews indicate a substantial amount of user discussion. I see those figures as a reason to investigate the app, not as proof that it will suit every financial situation.
The developer is Rocco Finance, Inc., and the app has passed the early experimental stage rather than appearing as a brand-new release. It was released on March 14, 2022, and has reached over one hundred thousand installs. That level of adoption makes it easier to understand why someone might consider it, but popularity does not remove the need to inspect the actual terms presented to an individual user.
In daily use, I would keep the workflow deliberately narrow. Open the app when I have a defined question, review the available information, record the important details privately, and close it when finished. I would not leave it open on a shared device or let another person browse through it out of curiosity. This routine is more valuable than trying to make the app serve as a general-purpose household finance center.
I would also avoid relying on memory after reviewing an offer. I would note the repayment date and total expected obligation in a private budget, then check whether that amount fits after essential expenses. If the calculation works only when everything goes perfectly, I would consider that too fragile. A short-term advance should not depend on skipping food, medicine, utilities, or another existing repayment.
Who should choose it, and who should look elsewhere
I think Rocco is worth considering for an adult who needs to explore a short-term cash option, understands that borrowing has consequences, and wants to begin the process from a phone. It may also suit someone who values a separate personal finance tool while coordinating household decisions verbally with a partner or relative.
I would skip it if the real need is shared expense management, long-term debt reduction, investment planning, or a complete record of household spending. I would also avoid using it as a repeated bridge between paydays. In those cases, a budget review, a bank conversation, a creditor arrangement, or professional financial guidance is likely to address the underlying problem better.
It is not the right choice for a child, a casual shared-device user, or anyone who cannot confidently explain how repayment will fit into the next budget. The Everyone rating describes the app’s general content classification, not the maturity needed to make a responsible financial decision. That distinction matters in a home where several people use the same phone.
My household verdict
After weighing the convenience against the responsibility, I see Rocco as a focused finance app rather than a household money hub. Its free availability and mobile format make it easy to investigate, and its cash advance focus may be useful when timing is the immediate problem. But I would keep the account private, involve other household members through a clear conversation, and compare the option with non-borrowing alternatives before accepting anything.
My recommendation is cautious but positive for the right adult user. Install it on a protected personal device, review every financial detail slowly, and decide repayment before requesting an advance. If you need a shared budget, a child-friendly money tool, or a long-term plan, choose something designed for that purpose instead. Used within firm boundaries, Rocco can be a practical place to explore short-term financial help; used casually on a shared device, it creates more confusion and risk than convenience.
Rocco - Fast Cash Advance FAQ
What is Rocco - Fast Cash Advance, and how does it work?
Rocco - Fast Cash Advance is a financial app designed to help eligible users request short-term cash advances through a mobile device. After creating an account, you generally provide personal and financial information, review any available offer, and choose whether to accept it. Approval, advance amounts, repayment terms, and delivery speed can vary based on eligibility and the information submitted.
Is Rocco - Fast Cash Advance a lender, and how much does it cost?
Before using Rocco, carefully check whether the app provides the advance directly or connects you with third-party lenders or financial service providers. Costs may include subscription charges, service fees, express-transfer fees, interest, or other charges depending on the offer. Read the complete agreement and fee disclosure before accepting money, because the total repayment amount may be higher than the advance received.
What information does Rocco require during registration?
A cash-advance application may request details such as your name, contact information, date of birth, bank-account information, employment or income data, and identity-verification documents. These details can be used to evaluate eligibility and process repayments. Before submitting anything, review the app’s privacy policy, understand how information is shared, and make sure you are comfortable granting the requested permissions.
How quickly can I receive money through Rocco?
The delivery time depends on approval, account verification, banking schedules, and the transfer method selected. Some users may see funds deposited quickly, while standard transfers can take longer, particularly on weekends or holidays. Any instant or expedited option may involve an additional fee. The app should display the expected arrival time and cost before you confirm the transaction.
What should I know about repayment and using Rocco safely?
Repayment is usually scheduled automatically from a linked bank account or according to the terms shown when the advance is accepted. Confirm the due date, total amount, cancellation rules, and consequences of a failed payment before proceeding. Never share login codes outside the official app, keep enough money available for repayment, and contact official support promptly if you notice an unfamiliar charge or cannot repay on time.











